Video
TEA & TAX Property Incorporation: MASSIVE Tax Benefit
Plays from YouTube in privacy-enhanced mode. The player only loads when you press play.
TEA & TAX Property Incorporation: MASSIVE Tax Benefit
In brief
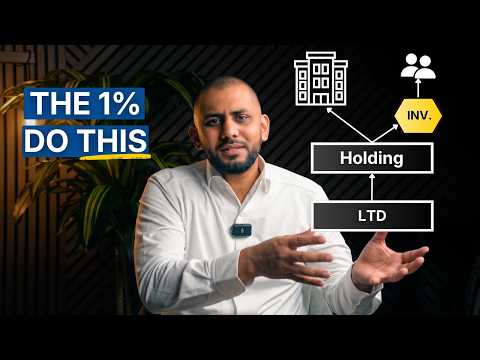
- When a property portfolio is moved into a company, the company is generally treated as acquiring the properties at market value.
- This sets a higher base cost for the company, which can reduce its future gains.
- The owner's own gain on the properties can be deferred through incorporation relief, but not removed.
- There are costs, in particular Stamp Duty Land Tax, and the full picture must be modelled.
What the base cost uplift is
An individual who owns a property has a base cost equal to what they paid, plus certain costs. If the property is then transferred to a company, the transfer is treated as a sale at market value, because the individual and the company are connected. The company's base cost is therefore the market value on the date of the transfer.
This means that the company's future gain, on a later sale, is measured from the higher value. Gains that built up before the transfer are not taxed in the company.
The effect for the owner
The owner has made a disposal at market value too, so there is a gain. Incorporation relief can defer this gain where the conditions are met. The relief rolls the gain into the shares the owner receives, and reduces the base cost of those shares. The tax comes into play when the owner sells the shares, so the gain remains but is moved to the owner's shares. If a relief is not available, the gain is charged at the time of the transfer.
Why the effect can be valuable
If the company later sells a property, the tax is charged on the uplift since incorporation and not on the original gain. In some cases, this is helpful if the owner expects to hold the shares for a long time, or pass them on in a way that gives a base cost uplift on death. Other families use a Family Investment Company or another route instead.
What has to be weighed against it
- SDLT is charged on the market value of the properties, with a higher rate on the whole in many cases for a company buying residential property
- legal fees and mortgage costs, including early repayment charges
- the loss of the individual's annual exempt amount on later sales
- double taxation on profits taken out of the company
- the effect of Section 24, which does not apply to companies
- the need to meet the business test for incorporation relief
A company is not the right answer for every landlord. See our page on property portfolio incorporation.
Frequently asked questions
Does incorporation remove the Capital Gains Tax?
It can defer it. The gain is rolled into the shares and taxed later.
Is the higher base cost available for every property?
It applies to those that are transferred. The rule about the business test and the SDLT cost need to be checked.
Do I need a valuation?
Yes. A professional valuation supports the market value used.
If you would like to talk this through for your own situation, please book a free call with our team.
Property Professionals
Want this applied to your situation?
Book a call with our team. Every plan is reviewed by a Chartered Tax Adviser, from the first call to the finished advice. We reply the same working day.
Go deeper on our specialist site: propertytaxadvisory.co.uk