eBook
Property Taxes – Ten Common Questions
Property Taxes – Ten Common Questions
This professionally created and verified eBook provides comprehensive advice to 10 common questions related to Property Taxation.
Landlords take heed! Where applicable, legislation and HMRC guidance is referenced.
Common property tax questions in brief
This page adds a written overview of the property tax topics landlords ask about most. It is not a summary of the eBook above, and your own figures and facts will differ.
- Landlords are taxed on rent, on gains when they sell, on purchase and on death.
- Rates change often, and the rules differ between individuals and companies.
- Records and early planning make most of the difference.
Tax on rent
Rental profit is the rent less allowable costs. Individuals cannot deduct mortgage interest from rent and receive a tax credit instead. From April 2027, the property income rates are 24%, 44% and 49% and the credit is at 24%. Companies deduct interest and pay corporation tax at 19% to 25%.
The rent a room scheme allows tax-free rent of up to £7,500 a year from a lodger in your own home.
Capital Gains Tax
Gains on the sale of property are taxed at 18% or 24%. Residential property gains by UK residents must be reported and paid within 60 days of completion. Your main home is usually covered by Private Residence Relief. Lettings and absences can limit this relief.
Stamp Duty Land Tax
Buyers of additional residential properties pay a surcharge, which is 5% from 31 October 2024. Rules for companies and for multiple purchases are complex.
Ownership by spouses
Owning a property jointly can use two sets of allowances and bands. The split of income follows the beneficial ownership, with a Form 17 election where the split is not equal.
Inheritance Tax
Property forms part of the estate. The nil-rate band is £325,000 and the residence nil-rate band is £175,000. Investment property does not usually attract business property relief.
Incorporation
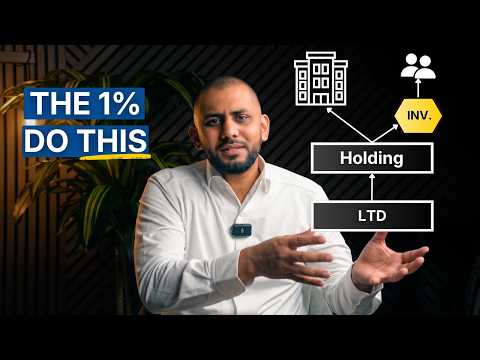
Moving a portfolio into a company can defer Capital Gains Tax through incorporation relief where there is a business, and the relief must be claimed for incorporations from 6 April 2026. SDLT and lender consent are practical issues. See our page on property portfolio incorporation.
Non-resident landlords
A landlord living abroad is taxed on UK rental income and must report a UK property sale within 60 days. See our page on non-UK resident landlords.
Making Tax Digital
Landlords with qualifying income above £50,000 must use Making Tax Digital for Income Tax from April 2026. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028.
Frequently asked questions
Can I deduct all my costs from rent?
Only those that are incurred wholly and exclusively for the letting and are revenue in nature.
Do I pay tax if I sell at a loss?
No. The loss should still be reported so it can be used later.
Is it worth taking advice before buying?
Yes. The structure is much easier to set up at the start.
If you would like to talk this through for your own situation, book a free call with our team.
Property Professionals
Want this applied to your situation?
Book a call with our team. Every plan is reviewed by a Chartered Tax Adviser, from the first call to the finished advice. We reply the same working day.
Go deeper on our specialist site: propertytaxadvisory.co.uk