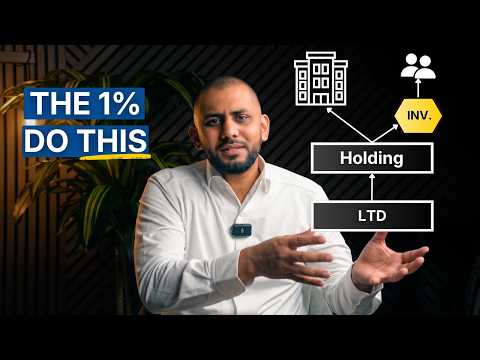
Video
Claiming CGT Incorporation Relief without a Partnership + What Constitutes a 'Business'?
Video link to be confirmed. The link for this recording is being checked before it appears here.
Claiming CGT Incorporation Relief without a Partnership + What Constitutes a 'Business'?
In brief
- Incorporation relief under section 162 of the Taxation of Chargeable Gains Act 1992 defers Capital Gains Tax when a business is transferred to a company in return for shares.
- A partnership is not required, but there must be a business.
- For incorporations from 6 April 2026 the relief must be claimed. It is no longer automatic.
- Whether a property portfolio is a business is the most common point of dispute.
What the relief does
When an individual transfers a business as a going concern, together with all its assets other than cash, to a company wholly or partly for shares, the gain on the assets can be rolled into the shares. No Capital Gains Tax is due at the time. The gain is deferred, and the base cost of the shares is reduced by the gain. The tax is paid when the shares are sold.
Do you need a partnership
No. A sole trader or an individual who owns property alone can qualify, as long as the conditions are met. The partnership cases are often discussed because the first successful claims involved partners. The key issue is the existence of a business, whoever carries it on.
What constitutes a business
The word is not fully defined in the tax legislation. Case law and HMRC guidance look at the level of activity, the organisation and the time spent. Ordinary management of a rental portfolio can be passive investment. The Ramsay case in the Upper Tribunal is the leading example, where a landlord who spent substantial time on the activity was found to be carrying on a business. HMRC has often used about 20 hours a week as a rough guide, but this is not a legal test.
Points that may show a business include:
- the number of properties and tenants
- the time spent on management, repairs and finding tenants
- whether you do the work yourself or use an agent
- the systems, records and contact with tenants
- whether you run the activity in a commercial way
The claim
For incorporations from 6 April 2026, the relief must be claimed, and the claim must be made by the individual. The shares should be issued for the business, with the consideration mainly in shares. If you take back a loan from the company or cash in addition, the relief is restricted. Take care with the company's own tax position, in particular Stamp Duty Land Tax, which is charged on the market value of property moved to a company by a connected person, without the partnership route.
Mortgage lenders must also agree. See our page on property portfolio incorporation.
Frequently asked questions
Is a single rental property a business?
Usually not, but it depends on the amount of work you do.
Can I claim if I use an agent?
It is harder to show a business. The activity still needs to go beyond ordinary investment.
Can a claim be refused?
Yes. HMRC may challenge a claim and the position should be documented in advance.
If you would like to talk this through for your own situation, book a free call with our team.
Property Professionals
Want this applied to your situation?
Book a call with our team. Every plan is reviewed by a Chartered Tax Adviser, from the first call to the finished advice. We reply the same working day.
Go deeper on our specialist site: propertytaxadvisory.co.uk